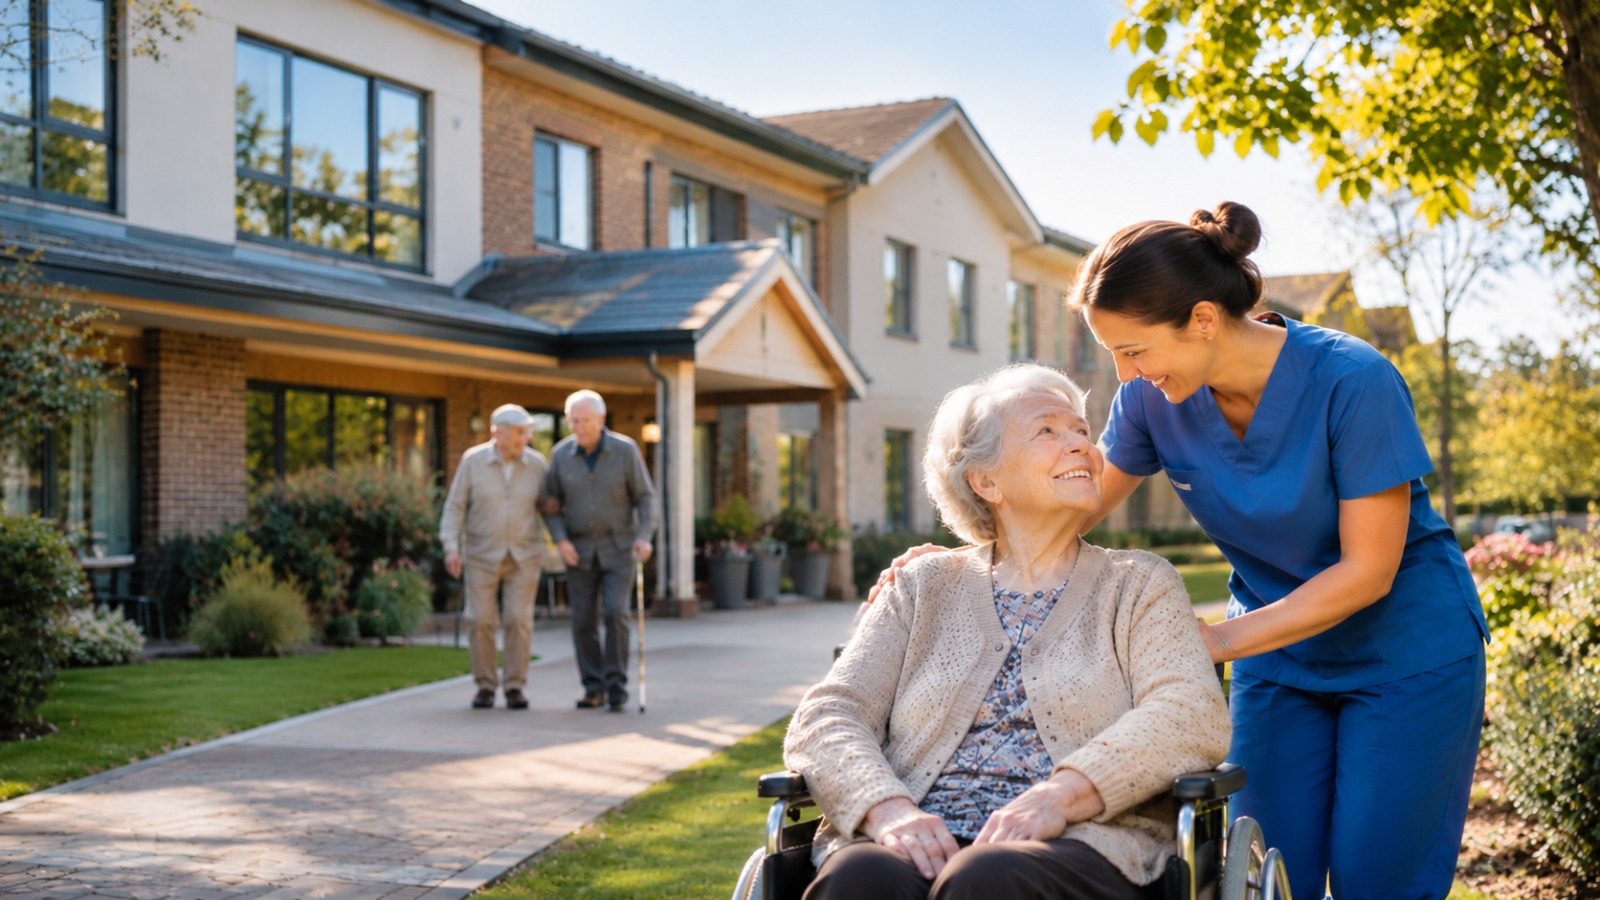
One of the best and most effective ways to grow a care home group is through acquisitions. This helps owners to expand an established business, increase capacity and strengthen its market position. However, business acquisitions are very costly and require careful financial planning. Understanding the process of portfolio lending and cross-collateralisation can help operators unlock capital and pursue new acquisition opportunities.
Acquiring an existing and running facility offers a faster route to expansion than developing a new facility. The facility will have its own client base and market presence, meaning you don’t have to start everything from scratch.
However, the cost of acquisition may be based on factors like property value, occupancy levels, operating costs, regulatory compliance and future investment requirements. With a good and well-planned financial strategy, businesses can expand while maintaining sufficient working capital.
For business owners, equity release through commercial refinancing allows access to capital tied up in existing properties. When the property value increases and the outstanding mortgage reduces, it becomes easier to refinance and release some of the available equity.
This allows businesses to purchase a new facility without the need to rely entirely on retained profits or additional personal investment. It is important for operators to consider increased repayments, interest costs and the impact of additional borrowing on cash flow.
Portfolio lending is a way to arrange finance against multiple properties under a broader lending structure. This way, the business won’t need to secure an individual mortgage for every acquisition as they can present the entire property portfolio to a lender.
The lenders will consider combined property values, rental or trading income, occupancy levels and overall financial performance. This can serve as a greater flexibility for established care home groups, considering refinancing existing facilities or purchasing additional properties.
Cross-collateralisation is a strategic approach that involves using multiple commercial properties as security for a single loan or wider lending facility.
For example, a care home business owner purchasing another care home may use the current property alongside the new acquisition as security.
However, this comes with many limitations and risks. When payments are not maintained, multiple properties could be affected. Additionally, the care home owner will need lender consent when selling or refinancing individual properties.
Using the right approach for care home finance can help care home business owners and operators with different ways to access capital and support acquisitions. Choosing between equity release, portfolio lending and cross-collateralisation to scale a care home business requires a detailed understanding of each method being used.
Working with a specialised mortgage broker can help explore suitable funding structures across mainstream and specialist lenders. AWS Private Finance serves as a trusted partner for care home business owners purchasing a second facility or expanding an established group. We provide the required guidance to help make acquisitions more manageable and support sustainable growth.
 1 Percent Mortgages – How Long Can they Last?
 £1m-plus mortgage borrowers pay over the odds
 A New Lending Market Landscape: What Should Borrowers Do?
 Affordability rules relaxed as house prices continue to rise
 Alternative Investments: Investing in Wine
 As Mortgage Choice Declines, Importance of Advice Increases
 As Mortgage Rates Start to Rise, Time to Secure that Large Loan
 As property prices hit 18-year high, will political turmoil have an impact on values?
 Asking prices rise but mortgages prove trickier to come by
 August: Housing market ‘mini boom’ while holiday lets heat up
Our mortgage advisers are here to help you find the best solution for your needs.
Enter your commercial property value to calculate stamp duty
YOUR HOME OR PROPERTY MAY BE REPOSSESSED IF YOU DO NOT KEEP REPAYMENTS ON YOUR MORTGAGE OR OTHER LOAN SECURED UPON IT.